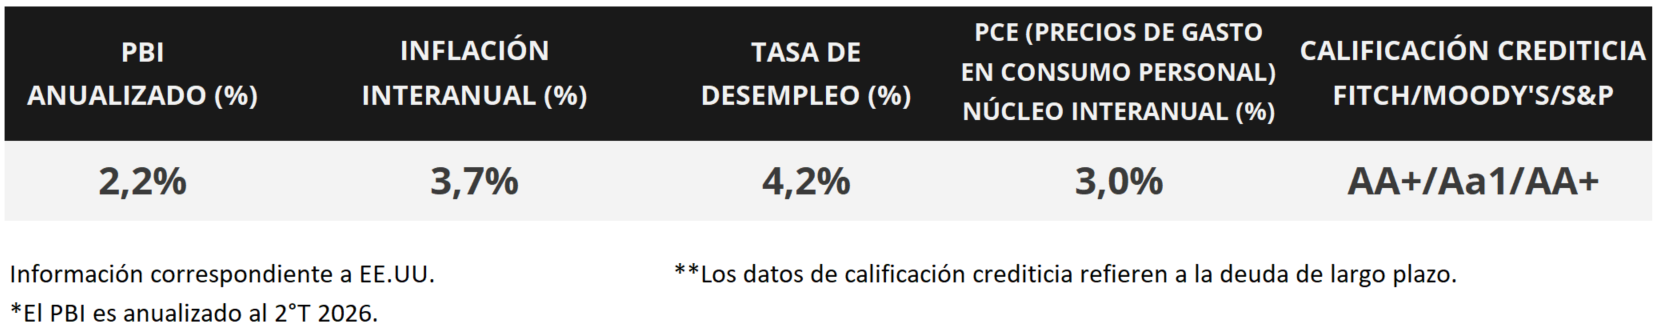

In the United States, retail inflation came in higher than expected. It rose by 0.6% month-on-month and 3.7% year-on-year, while the core measure (excluding food and energy) increased by 0.3% month-on-month—surpassing the 0.2% projection—and by 2.6% year-on-year, compared to 2.4% in August. Against this backdrop, the U.S. Treasury yield curve flattened across all maturities over the past week, with the 1-year note reaching 4.42% and the 10-year note hitting 5.09%. This week, attention will be focused on the release of preliminary Purchasing Managers' Index (PMI) data—a leading indicator of economic activity—for October, as well as third-quarter earnings reports from companies in the technology, financial, and consumer discretionary sectors. In the short term, the outlook suggests that inflation will remain above the central bank’s 2.0% target, supported by a resilient labor market; this is expected to keep interest rates at historically high levels. Consequently, investment-grade bonds are likely to offer higher nominal yields for a longer period, with the portion of the yield curve covering maturities of up to five years appearing particularly attractive.
Weekly Monitor
International
In the United States, the focus this week will be on the release of preliminary sectoral Purchasing Managers' Indices (PMIs)—leading indicators of economic activity—for October, as well as the University of Michigan’s inflation expectations survey for September, which points to a +4.7% rate over the next 12 months. In the Eurozone, sectoral PMIs for October will also be released, while in Latin America, data on retail sales in Mexico will be published.
In the United States, the Consumer Price Index (CPI) rose by +3.7% year-on-year in September, exceeding both the +3.6% expected by the analyst consensus and the +3.4% recorded in August. On a monthly basis, the index increased by +0.6%, up from +0.4% the previous month. Meanwhile, the core measure—which excludes food and energy—stood at +2.6% year-on-year, surpassing the consensus estimate and the +2.4% seen in August. The monthly change was +0.3%, compared to the +0.2% that had been anticipated.
Additionally, retail sales grew by +0.8% month-on-month in September, outperforming the +0.3% forecast by analysts. The core measure, which excludes the automotive sector, rose by +0.9% month-on-month—above the +0.6% projected, though lower than the +1.4% recorded in August. Furthermore, the Producer Price Index (PPI) posted a monthly increase of +1.3%, the largest since March 2022 and higher than the +0.6% expected. On a year-on-year basis, the index rose by +6.3%, while the core measure stood at +5.0%—both figures exceeding the consensus estimates.
Regarding the third-quarter corporate earnings season, companies such as Bank of America, Goldman Sachs, Citigroup, Morgan Stanley, BlackRock, Taiwan Semiconductor, ASML Holding, and UnitedHealth reported earnings per share (EPS) and revenue figures that beat analyst consensus estimates last week. This week, two of the so-called "Magnificent Seven"—META and Tesla—are set to report their results, alongside other companies including GE Aerospace, Netflix, General Motors, Procter & Gamble, IBM, RTX, and Lockheed Martin.
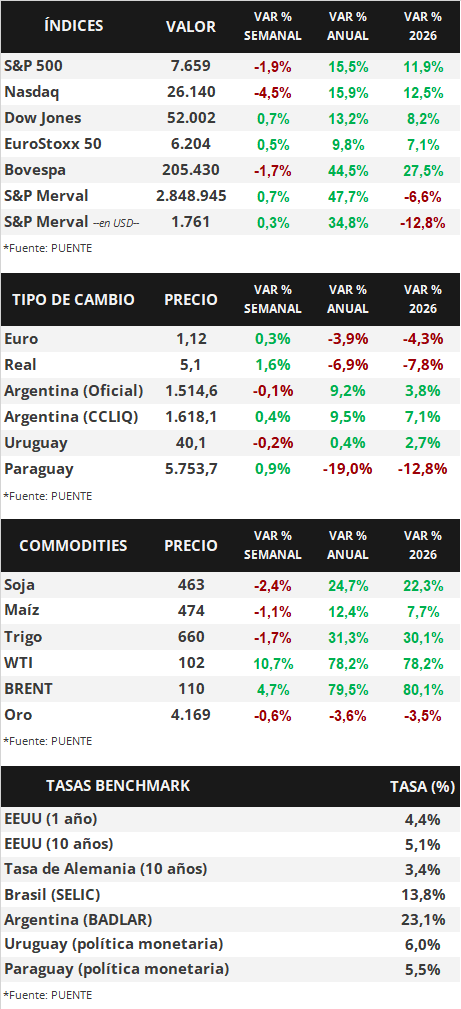
Against this backdrop, U.S. Treasury yields declined across the entire curve over the past week. The yield on the 1-year Treasury note fell from 4.44% to 4.42%, while the 3-year note yield retreated from 4.92% to 4.81%. Meanwhile, the 10-year Treasury yield moved from 5.24% to 5.09%. Investment-grade corporate bonds (tracked by the LQD ETF) closed with an average yield of 6.2%. In the equity markets, the Nasdaq and S&P 500 indices ended the week down 4.5% and 1.9%, respectively, while the Dow Jones rose by 0.7%.
In the Eurozone, the Consumer Price Index (CPI) for September rose by 0.6% month-over-month—in line with consensus expectations—while the year-over-year increase reached 3.8%. The EuroStoxx 50 index posted a weekly gain of 0.5%.
Finally, in Latin America, retail sales in Brazil grew by 0.1% month-over-month in August, falling short of market expectations. On a year-over-year basis, they increased by 0.4%. In Mexico, industrial production in August grew by 0.6% month-on-month and 3.5% year-on-year, exceeding projections of 0.0% and 2.6%, respectively.