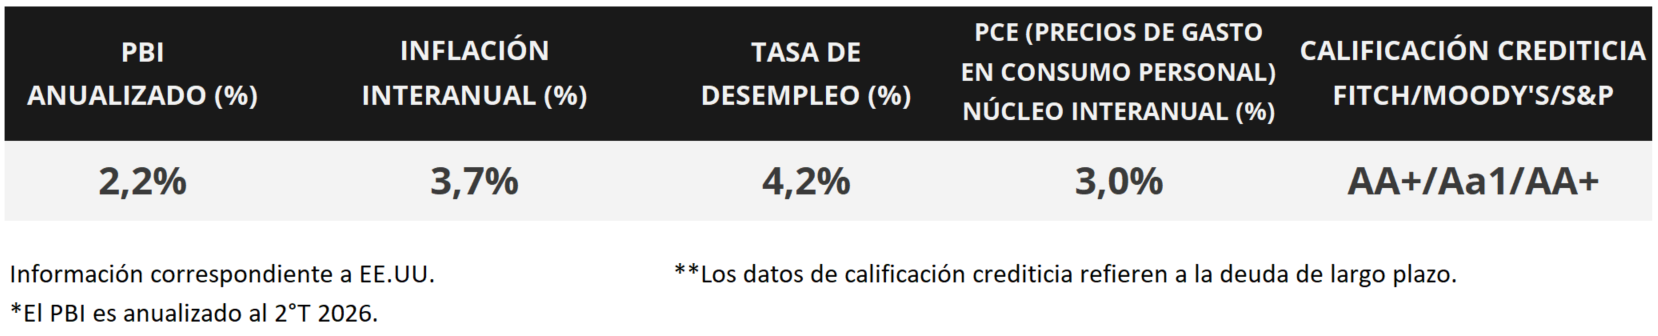

In the United States, the third-quarter corporate earnings season is underway, with 24% of companies having reported their results; of these, 83% have exceeded earnings-per-share (EPS) estimates, and 66% have surpassed revenue forecasts. Overall, companies are reporting earnings that are 2.1% higher than projected. Against this backdrop, the U.S. Treasury yield curve flattened across all maturities over the past week, with the 1-year Treasury note at 4.39% and the 10-year note at 5.00%. This week, attention will be focused on the Federal Reserve (Fed) meeting, where the benchmark interest rate is expected to remain unchanged at its current level of 4.00%. Additionally, third-quarter Gross Domestic Product (GDP) figures will be released—with an annualized growth projection of 3.0%—along with the Personal Consumption Expenditures (PCE) price index for September. The latter, which is the Fed’s preferred indicator for monetary policy decisions, is expected to show a 3.1% increase in its "core" reading (excluding food and energy). In the short term, the outlook suggests that inflation will remain above the Fed’s 2.0% target, while the labor market is expected to stay resilient—factors that will likely keep interest rates at historically high levels. This environment allows for higher nominal yields over a longer period for investment-grade bonds, with the portion of the yield curve representing maturities of up to 5 years appearing particularly attractive.
Weekly Monitor
International
In the United States, the focus this week will be on the Federal Reserve’s monetary policy meeting, with expectations that the benchmark interest rate will remain unchanged at its current level of 4.00%. Additionally, preliminary third-quarter GDP figures will be released—with growth projected at an annualized rate of +3.0%—along with the September PCE inflation data, a key metric for the Fed’s interest rate decisions; an annual increase of +3.6% is projected, with the core measure expected to rise by +3.1%. Meanwhile, the third-quarter corporate earnings season continues, featuring reports from three of the "Magnificent Seven" companies. In the Eurozone, third-quarter GDP data is set to be released, with an estimated annual increase of +1.1%, while the European Central Bank (ECB) will announce a decision on its benchmark interest rate, which is expected to remain unchanged at 2.65%. Finally, Mexico will release its third-quarter GDP, with an annualized growth projection of +2.3%, and Japan will hold a monetary policy meeting, where interest rates are expected to remain steady at 1.25%.
The third-quarter corporate earnings season is underway, with 24% of companies having reported their results; of these, 83% have exceeded earnings-per-share (EPS) projections, and 66% have surpassed revenue forecasts. Last week, companies including SpaceX, GE Aerospace, RTX Corp, General Motors, MSCI, Meta Platforms, Tesla, IBM, AT&T, and Abbott reported EPS and revenue figures that beat expectations. Netflix reported an EPS above estimates, while its revenue was in line with forecasts. Meanwhile, 3M, Blackstone, and American Express posted EPS figures that exceeded expectations, though their revenues fell short of projections. This week, the focus will be on the earnings reports of three of the “Magnificent Seven”—Microsoft, Amazon, and Alphabet—along with other notable companies such as Visa, Coca-Cola, Boeing, Verizon, Eli Lilly, Mastercard, Intel, Starbucks, ExxonMobil, AbbVie, and Chevron.
Regarding economic events in the United States, preliminary Purchasing Managers’ Index (PMI) data—leading indicators of economic activity—for October were released. The manufacturing PMI came in at 56 points, exceeding both forecasts and the September figure, while the services PMI reached 57.9 points, aligning with the consensus projection from analysts. It is worth noting that a reading above 50 points indicates expansion, while a reading below that threshold signals a contraction in activity.
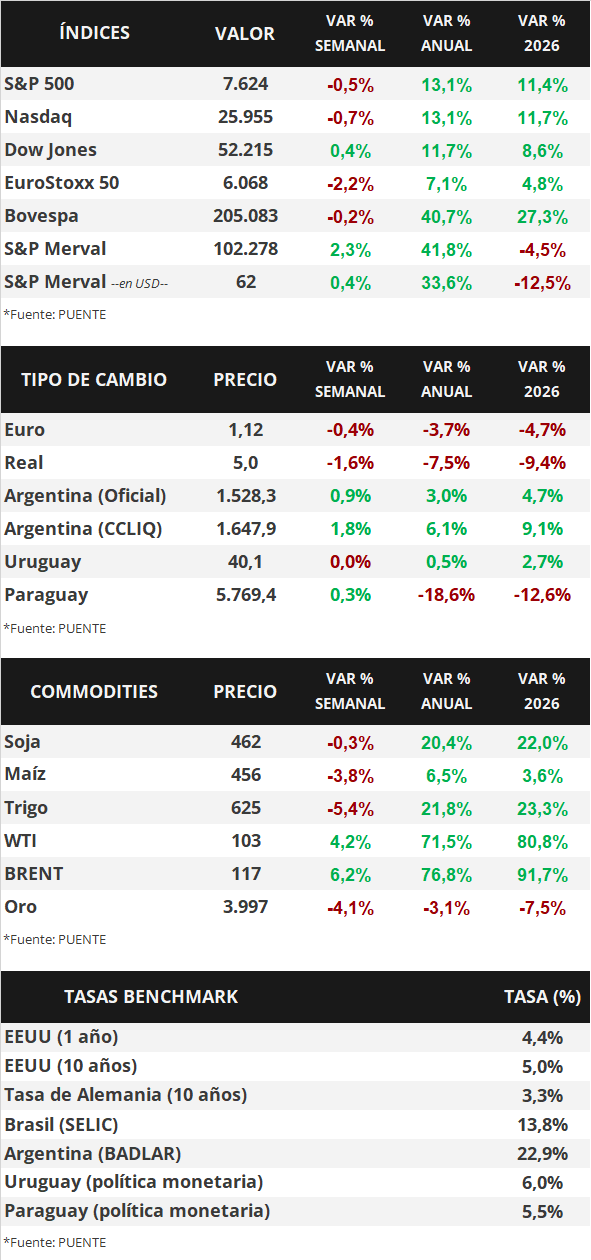
Against this backdrop, yields on U.S. Treasury bonds declined across the entire curve over the past week. The yield on the 1-year Treasury note fell from 4.42% to 4.39%, the 3-year note from 4.81% to 4.75%, and the 10-year note from 5.09% to 5.00%. Meanwhile, investment-grade corporate bonds (tracked by the LQD ETF) closed with an average yield of 6.1%. In the equity markets, major indices showed mixed performance, with the Dow Jones gaining 0.4%.
In Brazil, Luiz Inácio Lula da Silva, the candidate for the Workers' Party (PT), won the presidential runoff election, defeating Flávio Bolsonaro—representing the Liberal Party—by a margin of just over three percentage points. With this narrow victory, Lula was elected president for a fourth time, reversing the outcome of the first round of voting.
In the Eurozone, preliminary data for the October sectoral PMIs were released, showing declines compared to September. Specifically, the services sector PMI stood at 51.7 points—below the 52.5 expected—while the manufacturing PMI reached 52.4 points, compared to the 52.7 points projected.