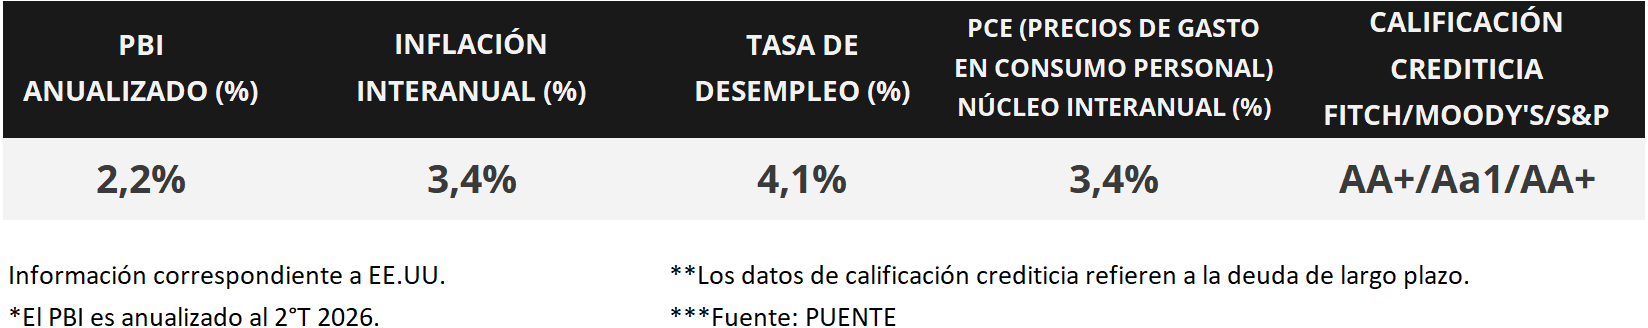

Minutes from the Federal Reserve (Fed) monetary policy meeting highlighted that the majority of committee members anticipate another interest rate hike this year—with rates currently in the 3.75%–4.0% range—in an effort to curb inflation, which remains above the Fed's target. Against this backdrop, the U.S. Treasury yield curve flattened across all maturities during the week; the 1-year bond yield stood at 4.44%, while the 10-year bond yielded 5.24%. September inflation data is due this week, with a year-over-year increase of 3.6% projected, and a 2.5% rise expected in the core measure (excluding food and energy). Additionally, the third-quarter corporate earnings season will kick off with the release of financial sector results. In the short term, the outlook points to inflation remaining above the Fed's 2.0% target alongside a resilient labor market, factors likely to keep interest rates at historically high levels. This environment allows for sustained high nominal yields on investment-grade bonds, making the short end of the yield curve—specifically maturities of up to five years—an attractive option.
Weekly Monitor
International
Attention in the United States this week will focus on the release of September retail inflation data, with expectations of a +3.6% annual increase and a +2.5% rise in the core measure. Additionally, the third-quarter corporate earnings season will kick off, with a focus on results from the financial sector. In the Eurozone, the September Consumer Price Index will also be released, with estimates pointing to a +3.8% increase and a +2.5% rise in the core measure.
Minutes from the Fed's latest monetary policy meeting revealed that the majority of committee members project an additional interest rate hike this year to curb inflation, which remains above the central bank's target. Furthermore, they reaffirmed that every decision will be based on macroeconomic data and its implications for the outlook and the balance of risks.
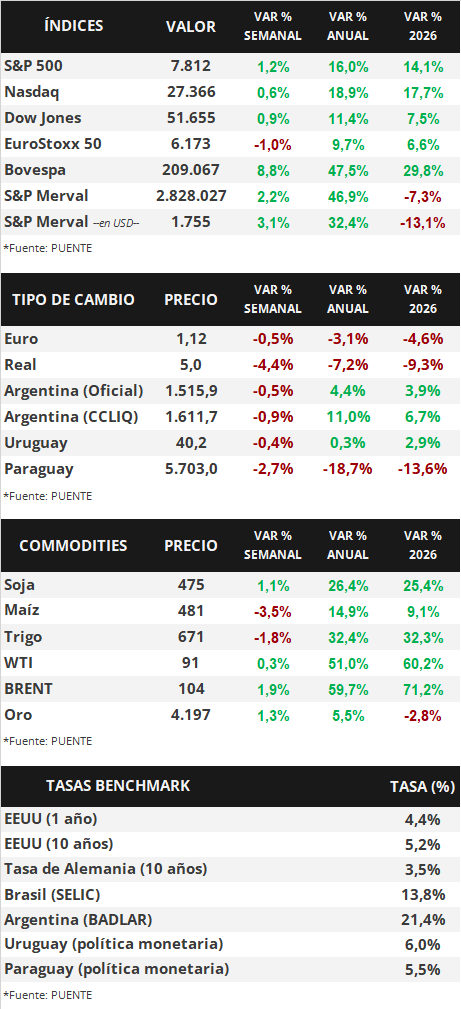
Against this backdrop, US Treasury yields compressed across the entire curve during the week. The 1-year bond yield moved from 4.45% to 4.44%, the 3-year bond from 4.95% to 4.92%, and the 10-year benchmark from 5.27% to 5.24%. Meanwhile, investment-grade corporate bonds (LQD ETF) closed with an average yield of 6.3%. Elsewhere, major US stock indices posted positive performances, led by the S&P 500 with a weekly gain of +1.2%.
In the Eurozone, wholesale inflation for August accelerated compared to July, recording a monthly increase of +1.9%. Additionally, the figure reached +8.2% year-on-year, the highest level since February 2023. Against this backdrop, the euro fell 0.5% during yesterday's trading session to 1.12 dollars per euro.
Finally, September inflation data was released for Brazil, Mexico, and Chile. Specifically, Brazil and Mexico recorded year-on-year increases of +4.6% and +3.5%—slightly above the consensus analyst estimates—while Chile’s figure came in at +4.1% annually, in line with expectations.