
International
Attention in the United States this week will focus on the release of September labor market data, with estimates pointing to the creation of 100,000 new jobs and an unemployment rate of 4.1%. Additionally, the Personal Consumption Expenditures (PCE) price index for August—the Federal Reserve's (Fed) preferred indicator for monetary policy decisions—will be released; projections indicate a +3.7% annual rise, and a +3.4% increase for the core measure (excluding food and energy). Meanwhile, the final estimate for second-quarter Gross Domestic Product (GDP) will also be announced, with expectations of +1.5% annualized growth. Elsewhere, Eurozone inflation figures for September are due, with forecasts predicting a +3.5% annual increase and a +2.6% rise in the core rate.
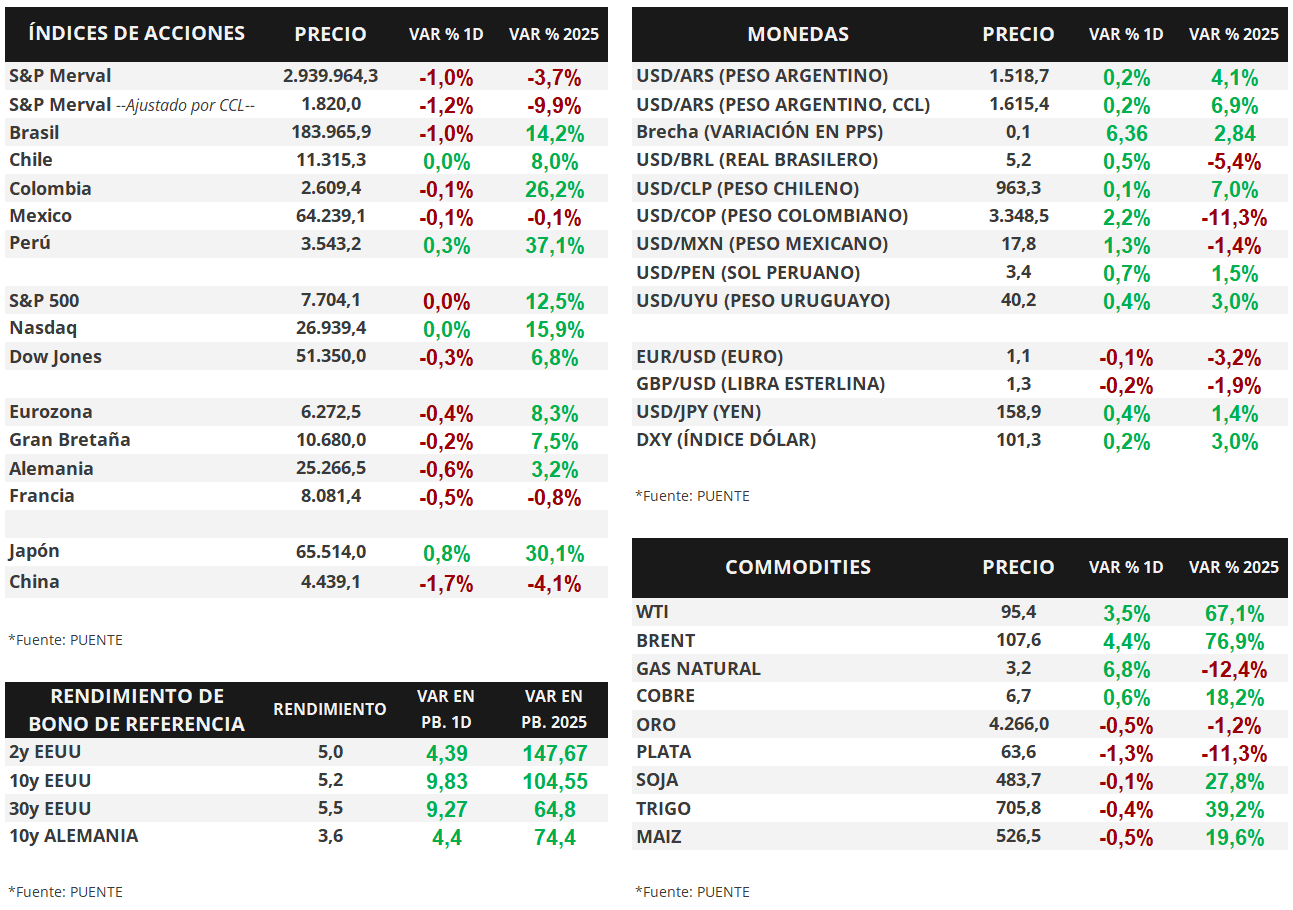
Major U.S. stock indices traded positively during the final session of the week. The Dow Jones led the trend with a +0.9% gain, followed by the S&P 500 and the Nasdaq, each rising +0.5%. With these performances, the indices have posted year-to-date gains of +7.8%, +13.1%, and +16.5%, respectively.
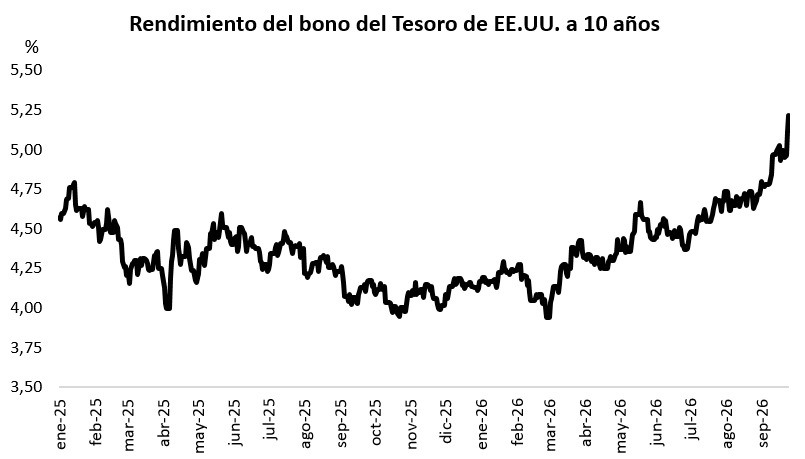
Meanwhile, U.S. Treasury yields declined across most maturities by Friday's close. The 1-year bond yield settled at 4.45% (down from 4.46%), the 3-year bond at 4.94% (compared to 5.02% on Thursday), and the benchmark 10-year bond ended at 5.17% (down from 5.21%). However, weekly performance showed significant widening, primarily in the short and medium segments of the curve.
Source: PUENTE